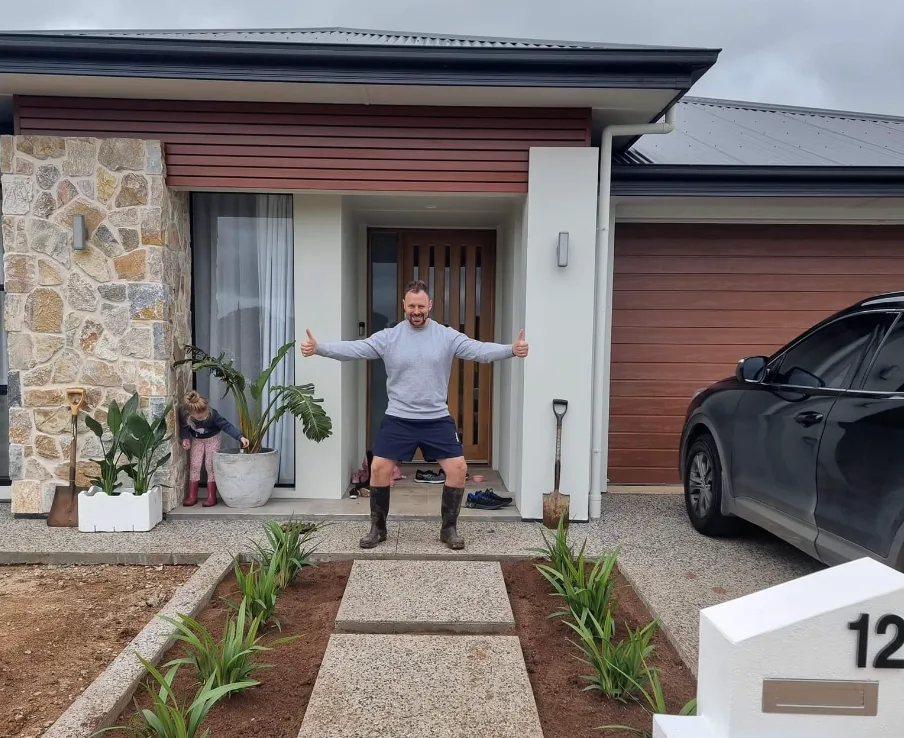
Serving Spring Mountain
Mortgage Broker Spring Mountain
Looking for a mortgage broker Spring Mountain buyers trust? Your Mortgage Broker Greenbank(/) arranges home loans across a panel of lenders for first buyers, builders and refinancers in one of Queensland's fastest growing corridors.
Looking for a Mortgage Broker in Spring Mountain?
Five years of approvals hit 3,461 against roughly 1,800 existing dwellings, so contracts, grants and childcare collide here.
Home Loans We Arrange in Spring Mountain
Refinancing, first home buyer loans, investment lending and construction finance arranged below, matched to how local buyers purchase:
Refinancing
Refinancing a Spring Mountain home means reviewing a loan written during the build or purchase phase, because more than half of local households are paying off their property and a median repayment near $2,000 a month deserves a periodic check.
First Home Buyer Loans
First home buyers dominate this suburb because the median age sits at twenty nine, nearly all stock is new four bedroom housing, and the Queensland first home offer, checked against our grant page, applies to plenty of contracts signed here.
Investment Property Loans
Investment lending in Spring Mountain works differently because owners occupy most streets, rentals are limited, and lenders weighing rental income against a median household income near $2,400 a week will look at how the proposed rent supports the borrowing position.
Construction and Renovation Loans
Construction finance carries weight here, because building approvals across five years reached 3,461 against only about 1,800 existing dwellings, which means progress payments, fixed price contracts and valuations on homes not yet built are ordinary business rather than edge cases.
Guarantor Loans
Guarantor loans suit buyers here, because a median age of twenty nine means many have parents holding equity elsewhere in Logan, and a family guarantee can bridge a deposit gap, provided everyone involved obtains independent legal and financial advice beforehand.
What Makes Financing a Spring Mountain Property Different
Only 2.8 per cent of dwellings were owned outright, making this a very new lending market:
New Estate Stock
Spring Mountain is a very new suburb, with dwelling approvals over five years reaching 3,461 against roughly 1,800 existing dwellings, so the stock is almost entirely recent detached homes and the lending question is new build finance rather than renovation.
Young Streets, Thin Comparables
Valuations on streets barely a decade old can swing, because comparable sales are thin when a subdivision is still selling, so we favour lenders whose valuers read house and land estates fairly rather than anchoring on distant or older sales.
Who Buys Here
Buyers here skew young and family sized: a median age of twenty nine, households averaging 3.3 people, and nearly eighty eight per cent of homes holding four or more bedrooms paint a picture of first and second home family buyers.
No Density Caps
At 98.3 per cent separate houses and zero apartments, the postcode restrictions, minimum floor area rules and lending caps that squeeze high density inner suburbs simply do not apply in the 4300 postcode, which widens your realistic lender options considerably.
Common Situations We See in Spring Mountain
A titled lot, a refinancer and a one ABN year tradie each hit different walls:
Refinancing a Recent Build
Many locals bought off the plan and are now two or three years into a loan written before recent rate movements, which raises a fair question about whether the structure they signed still fits the household they have become since.
Grant and Deposit Timing
A house and land package creates a timing trap, because the grant is paid at or after land settlement and the first drawdown, and contracts have collapsed on the mistaken assumption that government money arrives before the deposit is due.
Young Family Serviceability
With households earning a median of about $2,400 a week and repaying roughly $2,000 a month on their mortgage, serviceability maths generally works, but childcare costs, HELP debts and car repayments still trim capacity in ways applicants often underestimate alone.
Trading One Year
New estates attract tradies and small operators, and a self employed applicant with strong income on paper can still stumble when lenders want two years of returns, so alternative documentation paths matter more around here than the income percentile suggests.
How it works
Our Process
Four steps, clear durations: here is how a file moves from first call to settlement:
- 1
Speak to a Broker
Your conversation runs through your goals, income, debts and the property or package you have in mind, whether that is a titled lot in Spring Mountain or a refinance on a home you finished building a couple of years ago.
- 2
Capacity and Options Assessed
We then test capacity properly, running your figures against the policies of a panel of lenders rather than one rulebook, because shift penalties, childcare costs and HELP debts are treated differently from one institution to the next and margins matter.
- 3
Options in Writing
You receive your realistic options in writing, with rates, fees, features and honest timelines laid side by side, so the decision happens at your kitchen table with full information rather than over the phone with whatever a call centre remembers.
- 4
Application Through to Settlement
From application we quickly assemble the evidence pack, manage the valuation, chase conditions and coordinate solicitors and the lender's settlement team, watching every single contract date so your finance clause, land settlement or first progress claim never slips through unattended.
Why Choose Your Mortgage Broker Greenbank in Spring Mountain
A new brand cannot lean on reviews, so each point is checkable on our About page:
A Named Broker
Clients deal directly with Your Mortgage Broker Greenbank, a credit representative of a licensed business, rather than a rotating call centre, so the person who structures your loan is the same person who answers personally when you call, from enquiry to settlement.
Published Fee Structure
Our fee and commission structure is published, our commission is paid by lenders, and any fee chargeable to you is disclosed in writing before you commit, so the economics of the relationship sit entirely in the open from day one.
Documented Process and Timelines
Everything about how a file runs is written down on this site, from first conversation to settlement, including the realistic durations in weeks we see on files, because a new business without reviews owes you verifiable process rather than reassurance.
Worked Examples
Worked examples with real numbers appear right throughout this site, showing borrowing positions, timelines and costs under clearly stated assumptions, so you can see exactly how we reason before you ever hand over a pay slip or a signed contract.
Licensing and Compliance
Credit assistance is regulated and the framework protects you directly: here is who authorises us:
Credit Representative Status
Your Mortgage Broker Greenbank operates as a credit representative under [LICENSEE NAME], which holds Australian Credit Licence 389328, and our own representative number is 370592, so the full authorisation chain behind every single client conversation is always clearly documented and checkable.
Responsible Lending Obligations
Responsible lending obligations require us to verify your financial situation, assess whether a loan is suitable and not unsuitable, and keep records of that assessment, which is why document requests feel thorough even when your own application looks very straightforward.
Privacy and Your Data
Personal and financial information is collected only for arranging credit, handled under the Privacy Act, and shared with lenders and valuers strictly on a need to know basis, with our privacy policy explaining our retention, access and correction rights clearly.
How Complaints Work
If something goes wrong, raise it with us and we will respond within our published timeframe, and if you remain unsatisfied you can take the matter to the Australian Financial Complaints Authority, an external dispute resolution service, free of charge.
Getting a Better Rate on Your Spring Mountain Loan
Nobody can promise a figure, but these four levers genuinely move total cost:
Structure Beats the Headline
The headline figure matters less than structure: offset availability, redraw, fixed versus variable splits and fee loadings all shape total cost over a thirty year term, so we compare loan structures across a panel of lenders rather than headline numbers.
Check the Credit File
Ordering your credit report before you apply is a cheap insurance policy, because errors, forgotten store cards and clusters of recent enquiries reduce the amount lenders will advance, and fixing them takes weeks you do not want to spare mid-contract.
Twenty Per Cent Threshold
Crossing the twenty per cent threshold removes lenders mortgage insurance from the equation, and on newer Spring Mountain homes recent purchase prices give valuers solid comparables, so a review every couple of years may reveal you have crossed it already.
Review an Older Loan
If your loan was written during a build and rates or your circumstances have moved since, a structured review compares your current arrangement against the whole panel, and even a modest structural improvement compounds meaningfully across a long remaining term.
Where we work
Areas We Service
We service Greenbank, Forest Lake, Camira and Boronia Heights alongside Spring Mountain, so one broker handles the whole picture.
Questions answered
Frequently Asked Questions
Do you meet clients in Spring Mountain or work remotely?
We do both. Most conversations run by phone or video, though face to face meetings can be arranged.
What is the median price in Spring Mountain right now?
Medians move monthly, so we cannot quote one, but we will walk you through the current figures on a call.
How long does home loan approval take?
Roughly four to six weeks on a standard purchase, longer for construction, since lenders value the finished home.
Can you help with a Spring Mountain investment property?
Yes. Investment lending turns on how proposed rent stacks against your income and debts, so structure is worth deciding before you sign.
Do you charge a fee for your service?
Our commission on home loans is paid by the lender, so you generally pay nothing directly, and any fee is disclosed in writing first.
Which lenders do you have access to?
We work with a panel of lenders rather than one bank, so your file goes to whichever policy fits your situation.
Mortgage broker for Greenbank and the suburbs around it
Get in Touch
Call (07) 3523 7109 for a free Spring Mountain loan conversation, or message us and we will reply within one business day.