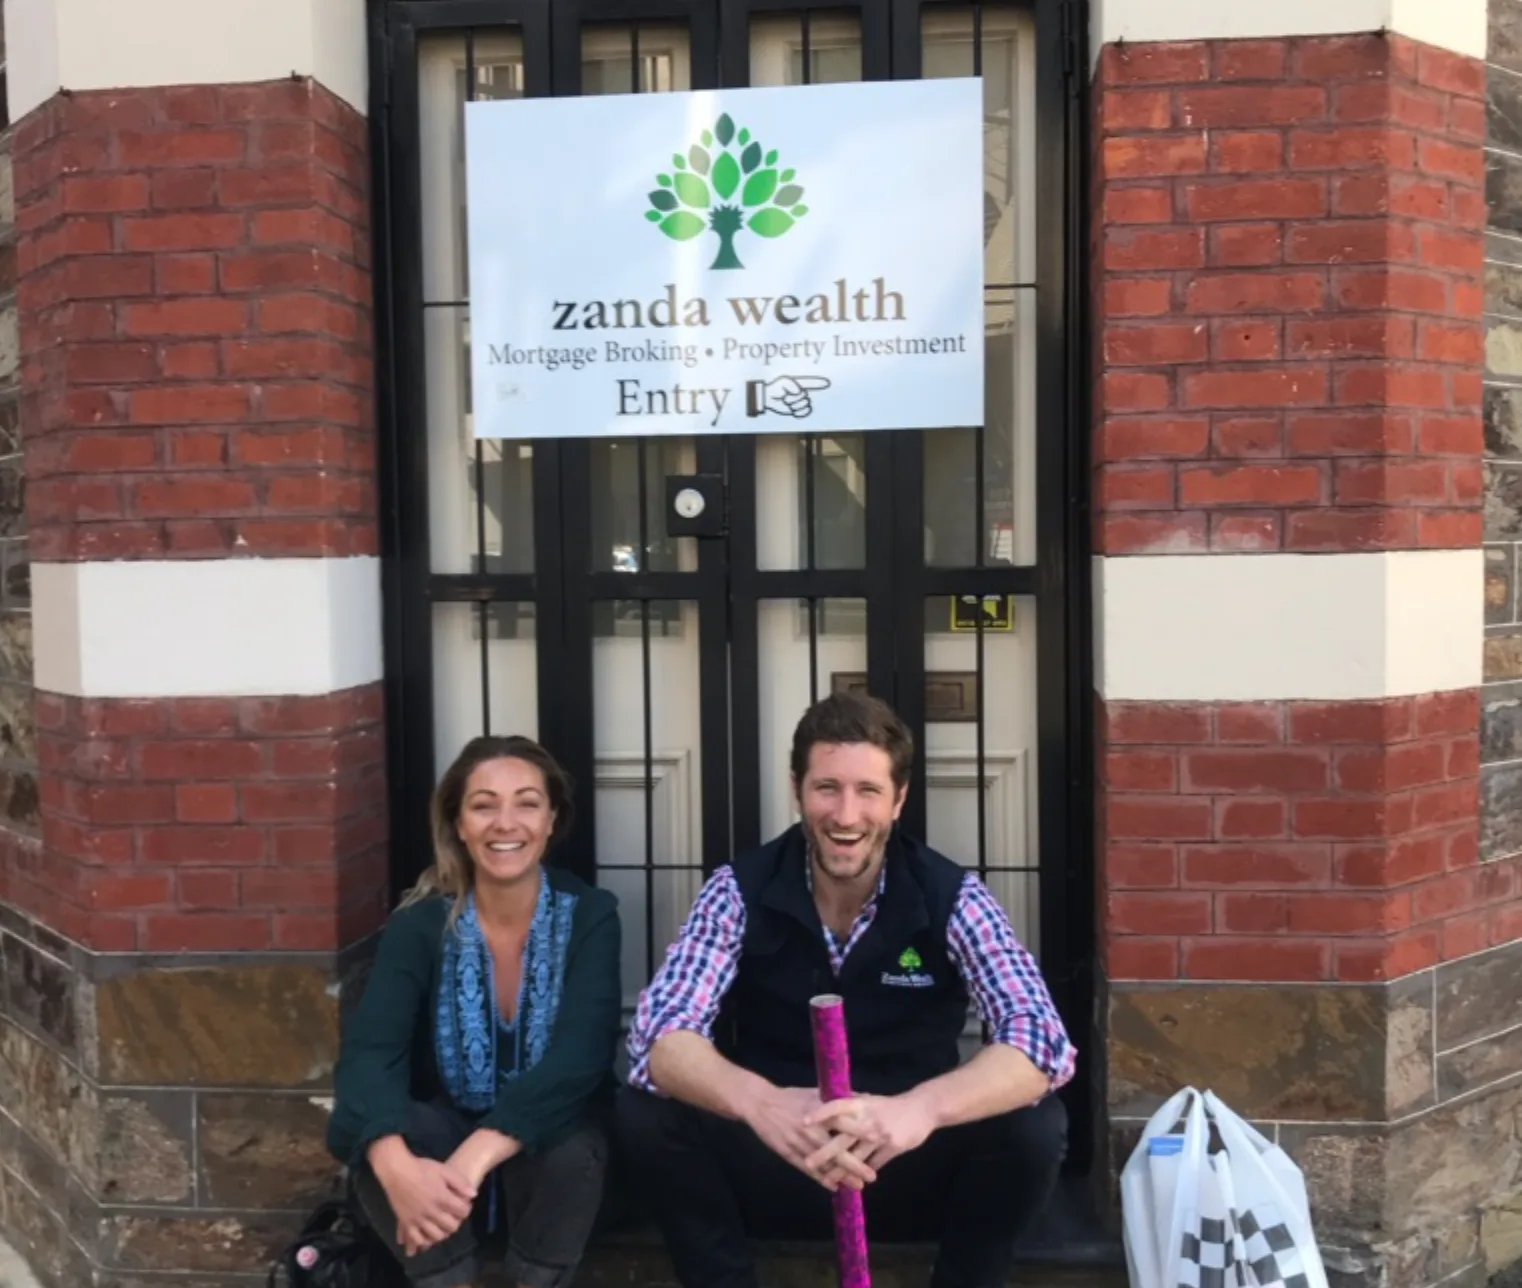
About us
About Your Mortgage Broker Greenbank
Your Mortgage Broker Greenbank arranges home loans for buyers and owners in Greenbank and the surrounding Logan corridors. This page sets out who we are, exactly how we are paid, and the licence arrangements behind every recommendation we make.
Why We Started a Broking Business in Greenbank
Too many capable local buyers were walking out of one bank with a no, believing that answer was the market's answer. A broking business exists precisely because it does not have to be, and this page explains who we are.
Who You Actually Deal With
Most broking brands are websites with a phone number behind them. This one is a named person with a licence number you can check, a qualification you can verify and a direct line that reaches the same desk that assessed your file. Three things follow from that:
The Broker on File
Your loan is handled by Your Mortgage Broker Greenbank, a credit representative of a business holding Australian Credit Licence 389328, who manages your file from the first call to settlement and specialises in residential home loans for families across Logan City.
Local Files, Real Numbers
Local experience matters here, because Greenbank's households carry a median mortgage repayment of about $2,015 a month on a median household income near $2,240 a week, and files shaped around acreage purchases, family guarantees and construction draws all appear regularly.
Direct Access, Always
When you ring, the person who answers is the person who assessed your file, from the first strategy call through to settlement day and the annual review afterwards, so nothing about your situation gets lost in a handoff between departments.
How We Get Paid, in Plain English
Here is the detail most broker sites leave buried in the Credit Guide you only see after committing: the full commission structure, written out where anyone can read it before handing over a financial life. It works like this:
Upfront commission
Trail commission
Fees
The honest complication: commission amounts vary a little between lenders, and pretending otherwise would be nonsense. That is a genuine conflict, and the answer is not denial but process. Every recommendation comes with the reasoning in writing, the shortlist compared side by side, and the commission structure of each option disclosed.
Is a broker worth it? A panel of lenders, however wide, is still not every lender in the market, and a bank branch is one lender. Between those two imperfect options, breadth plus written reasoning is the better bet for most borrowers, but you now have everything needed to judge that yourself.
Our Licence and Accreditations
Credentials are only useful if you can check them, so here are the four that govern this business, each with its number stated rather than described. Every one appears in the Credit Guide we provide before any credit assistance begins:
The Credit Licence
Australian credit law requires anyone arranging home loans to hold or operate under an Australian Credit Licence, and Your Mortgage Broker Greenbank operates as an authorised credit representative under licence 389328, held by [LICENSEE NAME], which governs our professional conduct and obligations.
Our Representative Number
Our representative number, 370592, is recorded publicly on the ASIC registers, so you can always independently confirm that the person arranging your finance is authorised to do so, rather than taking a marketing claim about credentials at face value.
Independent Complaints Pathway
The licence sits above every recommendation, and borrowers have an independent complaints pathway: the Australian Financial Complaints Authority is free to consumers, and our Complaints page sets out how to raise a concern with us first and escalate it afterwards.
AFCA and Your Complaints
Complaints are handled through the Australian Financial Complaints Authority, an independent external dispute resolution service, and our AFCA membership number appears on this page and in the Credit Guide, which means unresolved disputes go to an independent tribunal, not us.
How We Work With You
It starts with a free strategy call mapping your goals, income and deposit against the panel, then moves through assessment, lodgement and settlement with the process and timelines shared upfront, and it does not finish there: an annual review follows once your loan has settled.
Where we work
Areas We Service
From our Greenbank base we serve the Logan and Ipswich corridors, including Forest Lake, Camira, Boronia Heights, Munruben, New Beith and Spring Mountain.
Questions answered
Frequently Asked Questions
Who owns and runs Your Mortgage Broker Greenbank?
It is a representative of Zanda Wealth Mortgage Brokers, operated by Your Mortgage Broker Greenbank as a credit representative under an Australian Credit Licence held by [LICENSEE NAME], with no call centre or corporate layer between you and the person handling your loan.
Are you licensed to arrange home loans?
Yes. We operate as a credit representative under Australian Credit Licence 389328, held by [LICENSEE NAME], and our representative number 370592 is verifiable on the ASIC registers. Broking is credit assistance under the NCCP Act, and that authorisation covers our work.
How do you get paid if I don't pay a fee?
On most home loans the lender pays us a commission when your loan settles, plus a smaller trail payment while the loan runs. Neither comes from your pocket, and neither changes the rate or terms you are offered.
Do you get paid more for recommending certain lenders?
Honestly, commission amounts vary a little between lenders, so yes, a conflict exists. We manage it by putting the reasoning behind every recommendation in writing, comparing the shortlist side by side, and disclosing each option's commission structure upfront.
What happens if I have a complaint?
Raise it with us first and we will respond promptly and in writing. If it remains unresolved, you can take it to the Australian Financial Complaints Authority, a free and independent dispute resolution service whose decisions bind us.
How many lenders can you actually access?
We work with a panel of lenders spanning major banks, non-bank lenders and specialist providers. The exact current list is published in the Credit Guide we give you before any credit assistance begins, and no panel covers every lender.
Mortgage broker for Greenbank and the suburbs around it
Get in Touch
Call Your Mortgage Broker Greenbank on (07) 3523 7109 for a free, no-obligation strategy call, or read the first home owner grant page first if that applies to you. Twenty minutes is usually enough to know exactly where you stand.